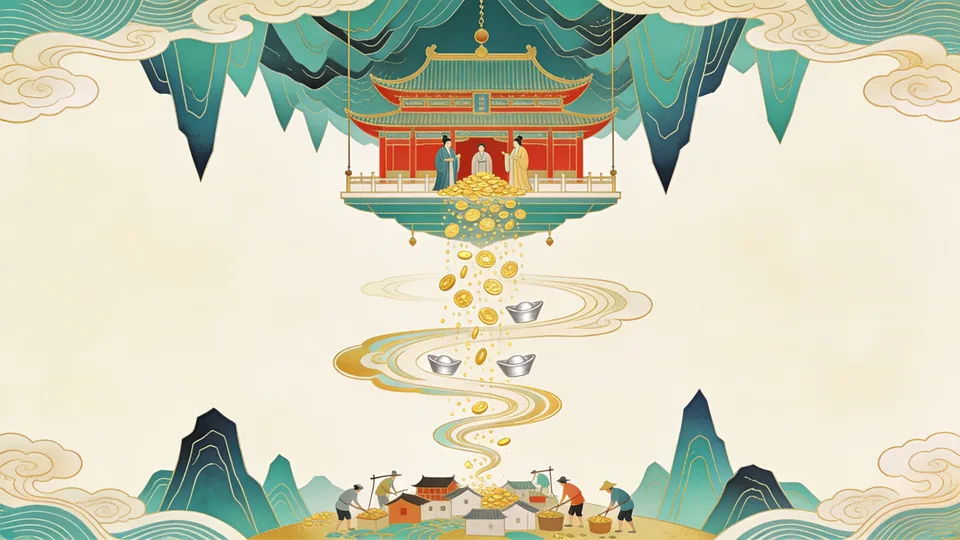
When the government replaces the paycheck, every layoff is a raise for shareholders.
In spring 2020 the economy stopped. Restaurants closed, flights emptied, and millions lost their jobs. By every traditional model, corporate profits should have collapsed. They held up almost completely, and stocks soon went on to records. Why?
The usual chain runs from layoffs to lost income, from lost income to less spending, and from less spending to falling revenue and profits. Once the government commits to backstopping nominal income and spending, that chain breaks. Layoffs stop threatening profits and start enhancing them, and the market turns upside down: bad news for workers becomes good news for capital.
Picture a town with one factory. It employs 100 workers, sells its goods to those same workers, and earns a small profit. Layoffs would be catastrophic, because fewer workers means fewer customers. Now suppose the government promises to keep total town spending constant. The factory lays off 50 workers, and the government sends them checks large enough that they keep buying at the same rate. Revenue is unchanged, the wage bill is halved, and profit doubles. The deficit replaces wages on the demand side without restoring the wage cost on the supply side.
Where profits come from
The accounting identity underneath is the Kalecki-Levy equation. Aggregate corporate profits equal:
Corporate Investment + Dividends + Current Account Surplus + Government Deficit + Household Deficit
This is bookkeeping, not theory. Each entity’s income is someone else’s spending, so every dollar of profit has to come from one of these sources. In aggregate, profits are not earned by being clever; they are injected.
In the U.S., the other terms rarely carry much weight. Investment fluctuates, dividends flow back to shareholders, the current account has been mildly negative for decades, and households save more than they spend. Which means in a low-investment, household-saving regime, the government deficit is what’s keeping corporate profits positive at all. In WWII, federal deficits reached about 22% of GNP and pre-tax corporate profits about 12%, among the highest in U.S. history. Only a 90%+ excess profits tax limited the after-tax gain: the state injected the income and clawed back the surplus, because the circuit was too visible to pretend the gains were earned. In 2020 the same mechanism ran without the tax, and that is why profits held. The Kalecki-Levy equation predicted it; almost no one was using it.
Bad news becomes good news
Push the town to its limit. A permanent virus keeps everyone indoors and real activity halves. Under laissez-faire, equity portfolios are destroyed. Under a regime that targets nominal spending, the nominal value of those portfolios goes up. The injected money still has to land somewhere, so spending shifts from closed restaurants to open grocery stores, and a diversified owner of both loses no net revenue. Meanwhile desperate labor accepts lower wages and rates fall to zero, so margins expand and discount rates compress.
Once investors understand this, the information environment inverts. Layoffs and contraction unlock more deficit and more rate cuts, so the downside is capped. Strong data earns patience rather than tightening, so the upside stays open. The central bank put becomes a fiscal-monetary put. A strong jobs report read as bullish, or a weak one as bearish, is reading the old book: in the upside-down regime, the news doesn’t matter; the policy reaction to the news matters, and the reaction is asymmetric in the direction of capital.
The Fed is a small player here. Put precisely, fiscal regimes that target nominal income and spending sever the link between economic distress and corporate revenue, turning labor weakness into shareholder strength through the accounting identity that ties profits to deficits. The real machine is the Treasury check that lands in the laid-off worker’s account and gets spent on something they would have bought anyway.
What breaks it
The machine has two weak points. The first is that fiscal stimulus only works if recipients spend it. In April 2020 the household saving rate hit 33%, against a normal 7–10%. If the town’s laid-off workers bank their checks, the factory’s revenue is not supported and the injection dries up at the source. A trillion-dollar deficit sitting in savings accounts is monetary noise; velocity matters as much as size.
The second is inflation. The regime injects nominal demand without matching real supply, and it works only while the gap stays inside the noise. When goods prices catch up with asset prices, the patient central bank turns hawkish, the generous fiscal authority turns constrained, and the put is withdrawn from under the leverage built on it. This is the Minsky failure mode: every quarter of manufactured stability draws in more capital to harvest it, so the eventual repricing becomes a cascade.
The bet implicit in record equity multiples is that the policymakers can run a permanent fiscal-monetary backstop without ever provoking the inflation that would force them to stop. The historical record on suppressing inflation by fiat is short and unflattering. Until that bet is settled, equity prices are less a measure of the town’s productive economy than of the government’s willingness to keep the factory’s customers paid.
References:
- Jesse Livermore, Upside-Down Markets: Profits, Inflation and Equity Valuation in Fiscal Policy Regimes, OSAM (2020)