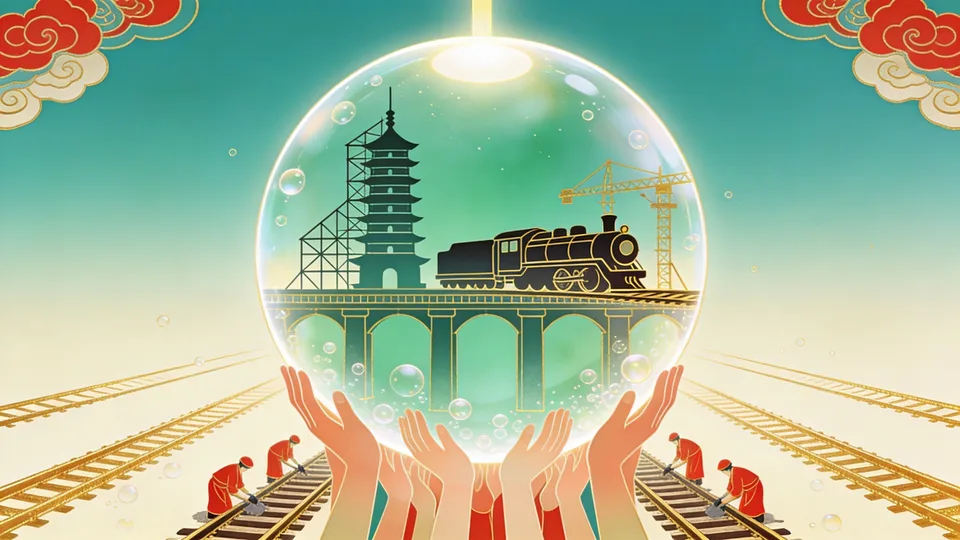
The dot-com investors lost their fortunes. The rest of us got the fiber.
Imagine pitching a railroad across a continent. It costs more than any one investor can carry. It needs belief from people who have never seen a train, and it only pays off if hundreds of other businesses (towns, mills, shippers, suppliers) bet on its existence at the same time. Each of them is waiting to see whether the others commit first. No rational individual moves, so nothing gets built.
And yet the rails got laid. Byrne Hobart and Tobias Huber’s Boom argues that they got laid because of the thing we usually blame: the mania. If everyone believes everyone else will commit, the capital flows, the track goes down, the towns appear, and the future the bubble described becomes the future the bubble created. The bust that followed was the price of the rails that remained. Most of us were taught that bubbles are a pathology a well-run economy should prevent. Boom turns that around: Suppressing bubbles is not prudence. It is the act that locks a civilization into stagnation.
Why the railroad needed a mania
The railroad problem is general. Apollo, the Manhattan Project, the internet and crypto all needed simultaneous commitment: capital, talent, suppliers, regulators and customers moving at once. Because nobody can rationally commit until the others do, everyone waits, which is the bad Nash equilibrium that holds even when everyone privately knows the right move.
A bubble breaks the wait. The shared excitement suspends the cost-benefit calculation that would otherwise freeze each actor. The bubble is the ritual by which a counterfactual future becomes simultaneously believed by enough people that the resources to build it actually flow. Belief, capital and talent show up at the same address, not because each was independently rational but because each was mimetically synchronized.
The uncomfortable part is that this is the same Girardian engine the garden’s mimetic markets note treats as pathology: people wanting what others want until the cascade inflates past reality and the crash discharges it. Boom doesn’t deny any of that. Its point is that a bubble is simultaneously a mimetic crisis seeking discharge AND the coordination mechanism that builds the rails the discharge will leave behind. Pathology and productivity describe the same process from opposite ends of its life.
Telling a good bubble from a bad one
If both kinds feel the same from inside, the test has to come afterwards: what is left standing once the fortunes have evaporated? Railroad track. The dark fiber laid during the dot-com boom, which the next decade ran on. A generation of engineers whose training the mania paid for. Unproductive bubbles leave only a redistributed balance sheet, wealth moved from the late buyers to the early ones with no durable artifact. Tulips. Beanie Babies.
The investor inside the bubble cannot reliably tell which one he is in, because both feel like genuine discovery. Society as a whole, however, can tell in retrospect: count the surviving infrastructure, not the surviving fortunes.
This is also the strongest objection to the book. “Encourage the good bubbles and prevent the bad ones” sounds sensible, but it is unfalsifiable in real time. The residue only becomes visible after the bust, and no policy machinery exists to tell the railroad from the tulip in advance. So the choice is not between good and bad bubbles. It is between permitting manias, some of which will be tulips, and suppressing them all.
The cost of smoothing
Hobart and Huber inherit Peter Thiel and Tyler Cowen’s diagnosis that progress has slowed since roughly 1970. Capital is allocated efficiently but timidly. Returns come from optimizing what exists rather than from opening frontiers. Modern policy, from central-bank smoothing to regulatory caution toward speculation, is built on the theory that a competent economy minimizes bubbles. But a smoothed market lets existing capital harvest existing returns while starving the manias that would have funded the next railroad.
The Cantillon dynamic from Broken Money sharpens the picture. When being close to newly created money is the best source of return, the smart move is not to fund frontier technology but to lever up existing assets near the source. Asset prices inflate while industry stays the same. The economy is full of returns and empty of futures.
Seen this way, bubbles are the civilization-scale equivalent of the positive orientation: an organism running toward something rather than away from something. An economy organized to avoid losses can see the cost of every bust, because busts are loud. It cannot see the railroads that were never started, because they are silent.
That is the book’s real reframe of rationality. Locally rational behavior, added up, produces stagnation whenever the frontier needs a synchronized commitment that no rational actor will start. Some of what looks like waste during the mania is the price of coordination, and some of what looks like prudence during the suppression is the price of stagnation. A civilization that permits a bubble is betting that the residue will be worth more than the wealth the mania destroys. AI, nuclear, biotech and space are the candidate frontiers now, and whether any of today’s manias is a railroad or a tulip is something only the residue will tell.
References:
- Byrne Hobart and Tobias Huber, Boom: Bubbles and the End of Stagnation (2024)
- Byrne Hobart, Manias and Mimesis, The Diff
- René Girard, Violence and the Sacred